Services · Quantitative Analytics Testing

Quantitative Analytics Testing

Testing quantitative finance software takes more than QA skill — you need someone who can look at a pricing model's output and know whether the number is actually right, not just whether the test passed. Our quant analysts hold FRM and CFA certifications and bring real Quant Finance domain understanding to validating various kinds of analytics for over 150+ asset classes.

Grounded in real quant methodology
  • Binomial & Black-Scholes
  • Greeks & Sensitivity
  • VaR & Tail-Risk
  • Scenario & Stress Analytics
validate · risk-engine.py

Reconcile pricing model output against reference values.

  • Binomial model: within ±0.01% tolerance
  • Greeks sensitivity: verified
  • Audit trail: complete
Validated — cleared for production
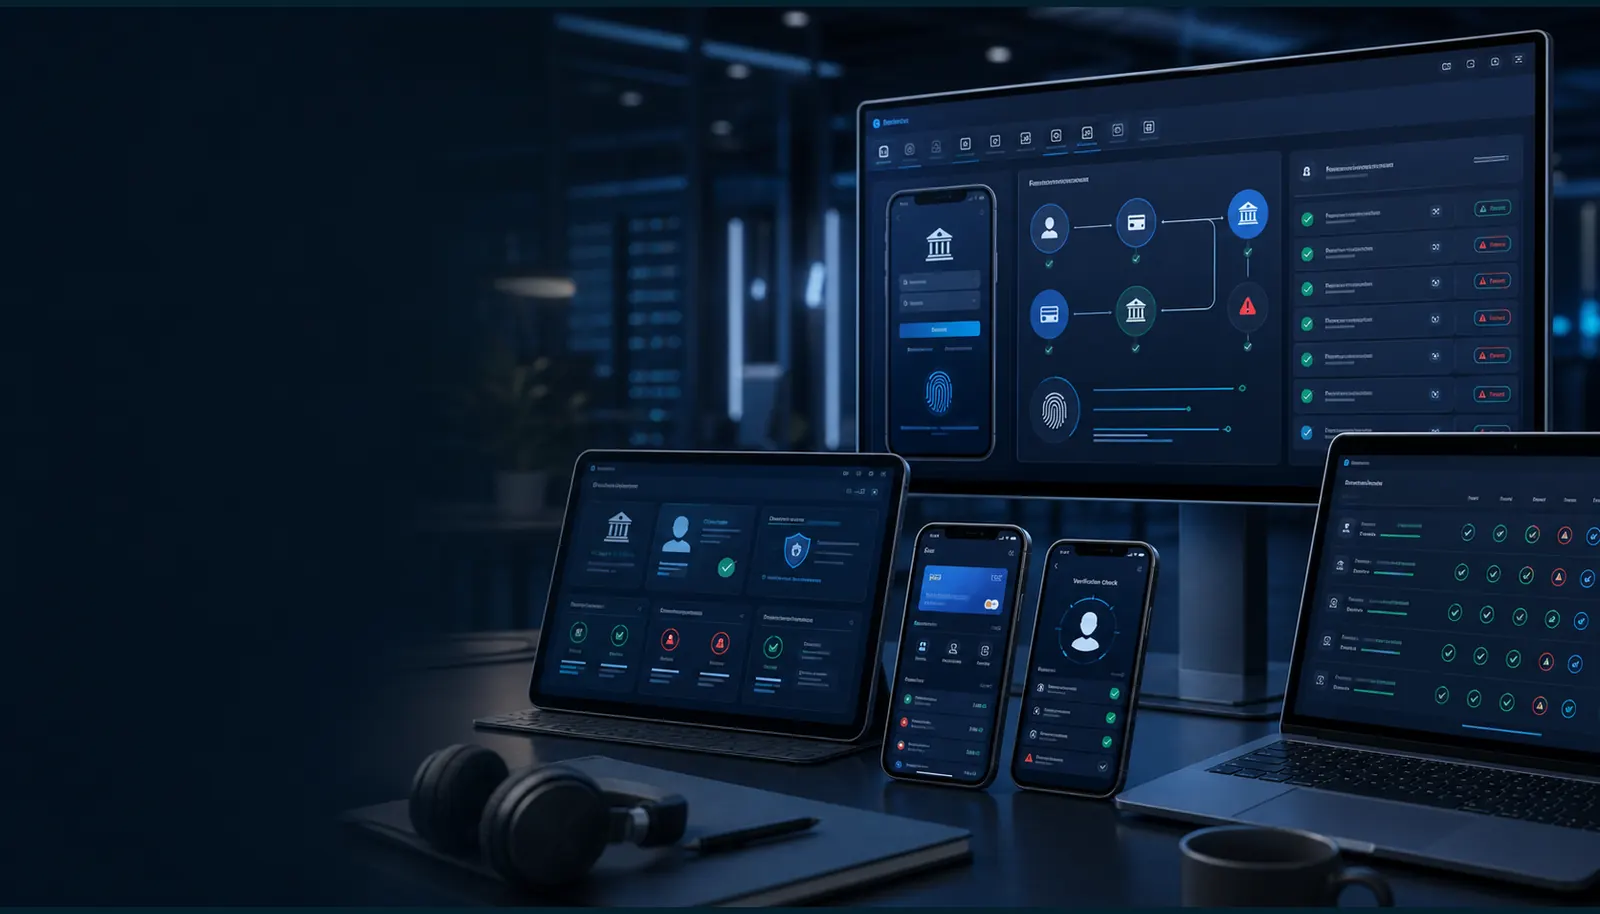
Dark fintech dashboard mockup across a monitor, tablet and phones, showing identity verification, a bank icon and pass/fail checklist rows

Financial Model & Pricing Validation

We validate the calculations behind options and derivatives pricing models — checking that a binomial model, or whatever pricing methodology your system uses, produces results that hold up against known reference values, not just that the code runs without an error.

  • Options and derivatives pricing model validation (binomial and other standard methodologies)
  • Reference-value and edge-case testing against known correct outputs
  • Sensitivity analysis testing (the Greeks) for pricing model accuracy
  • Regression testing when pricing logic or market assumptions change
Hands typing on a laptop beneath translucent dashboard panels showing performance charts and progress rings

Risk/Stress Test Analytics Validation

Your risk platform calculates VaR and runs the stress scenarios; we validate the analytics behind both. We check that VaR and tail-risk figures are computed correctly, and that each scenario, from a replayed historical crisis to a hypothetical 15% drop in biotech in a week, is applied as specified and reports exposure and P&L that match independent reference values.

  • Historical-scenario and crisis-replay results validated against known market outcomes
  • Shock-scenario analytics validated for hypothetical and geopolitical events across correlated asset classes
  • VaR and tail-risk validation against extreme-move exceedance behavior
  • Regression testing for risk engines through platform changes and market condition shifts
A businessperson's hand touching a glowing compliance interface with a checklist, scales of justice and gavel icons

Regulatory & Compliance Testing

Financial software carries compliance obligations most QA teams aren't equipped to validate against. We test for the regulatory reporting accuracy, audit-trail completeness, and data-handling controls that a compliance review will actually check for — before a regulator or auditor finds the gap.

  • Regulatory reporting accuracy and completeness testing
  • Audit-trail and data-lineage verification
  • Data-handling and access-control validation for regulated financial data
  • Test documentation structured for compliance and audit review

Let's talk about your quant testing needs

Tell us what's running — risk engine, pricing model, trading connectivity — and we'll scope the validation.